One Nation has opened a new front in Australia’s culture wars after criticising National Australia Bank for offering Sharia-compliant finance products to Muslim customers.
The dispute has quickly attracted attention because it combines several issues that already generate strong public debate: banking, religion, multiculturalism and the role major corporations play in accommodating different communities.
At the centre of the controversy is NAB’s Islamic finance division, which provides financial products structured to comply with Islamic principles that prohibit the charging or payment of interest.
One Nation argues the arrangement raises serious questions about whether Australia’s financial system should be creating specialised products based on religious requirements.
The party’s criticism has triggered a wider discussion about fairness, customer choice and how financial institutions respond to Australia’s increasingly diverse population.
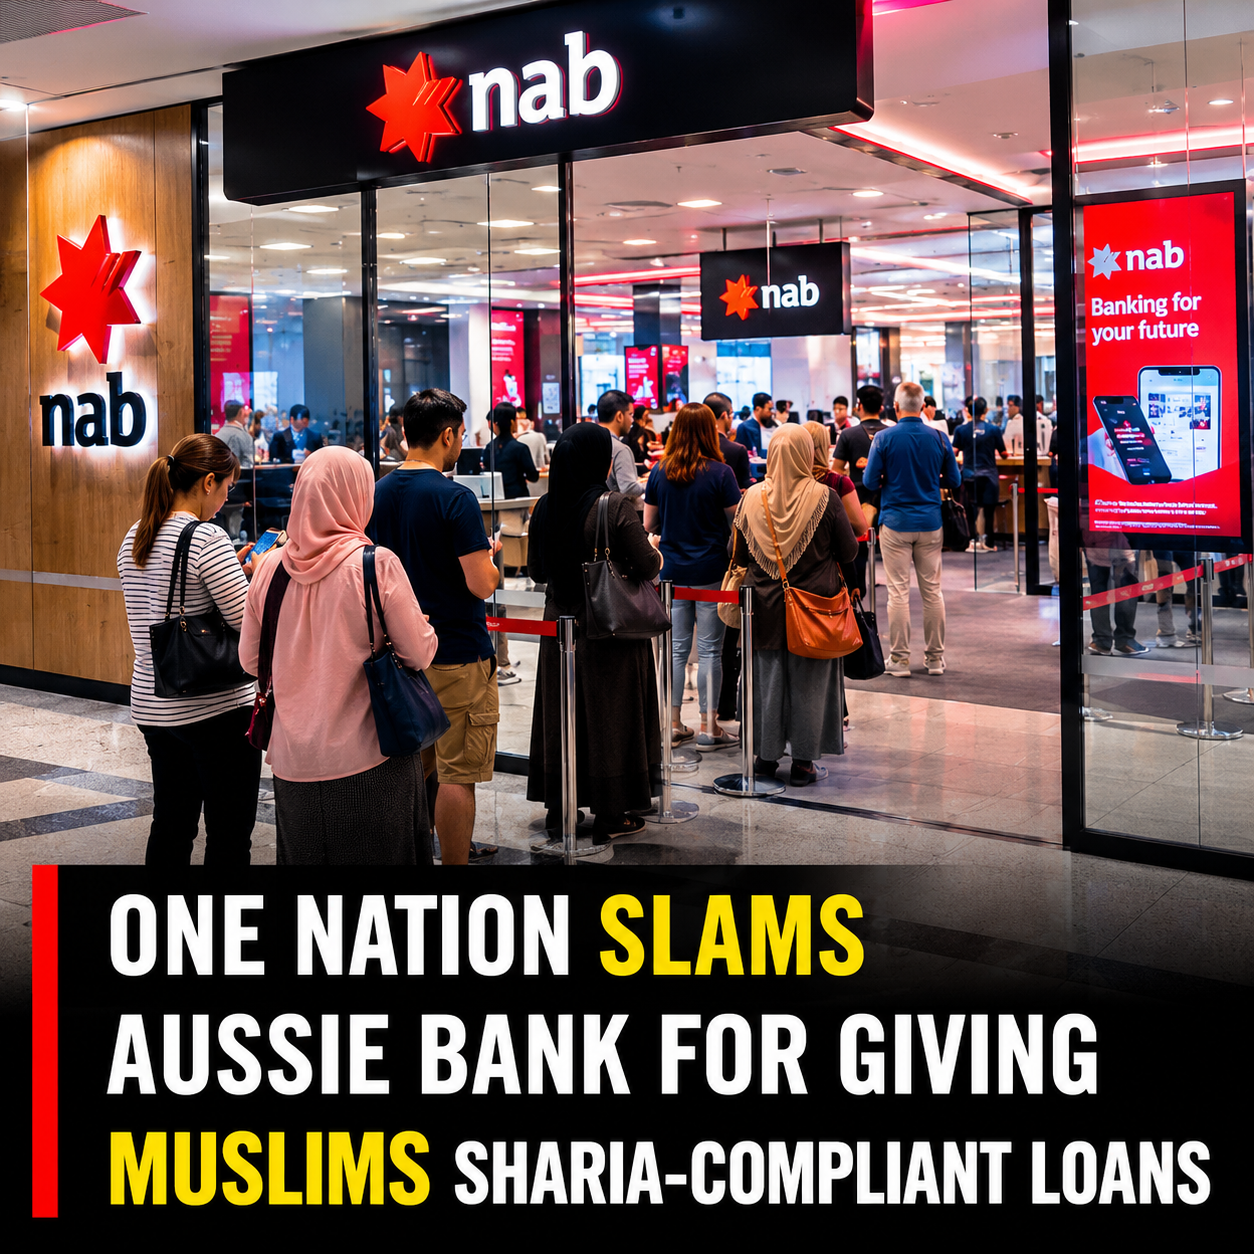
The issue emerged after One Nation highlighted NAB’s Islamic finance services and questioned why one of Australia’s largest banks was offering products specifically designed to meet Sharia requirements.
Party representatives argued that the move does not sit comfortably with many Australians and suggested banks should operate under the same financial framework for all customers.
The criticism quickly spread through social media and political commentary circles, where supporters and opponents of the party began debating the issue.
For One Nation, the controversy fits within a broader political message that has focused heavily on national identity, immigration, integration and the preservation of Australian institutions.
The party has frequently argued that newcomers should adapt to Australian norms rather than expecting institutions to adapt to them.
Supporters of the latest criticism say the debate is not about religion itself but about whether major corporations should provide services designed around specific religious doctrines.
They argue that banking products should be neutral and universally applied regardless of faith.
Others see the issue very differently.
They argue that Islamic finance is simply another example of businesses responding to customer demand.
From that perspective, banks routinely create specialised products for different groups of customers, industries and communities.
Supporters of Islamic finance say the principle is no different.
NAB has been involved in Islamic finance for years and has publicly promoted its expertise in providing Sharia-compliant funding solutions to business customers.
The bank says its Islamic finance products are structured differently from conventional lending but are designed to achieve comparable commercial outcomes while remaining compliant with Islamic principles.
The products are primarily aimed at businesses, commercial property transactions and other larger-scale financing arrangements.
NAB has previously described itself as the only major Australian bank offering a dedicated Islamic finance solution for business customers.
Islamic finance itself is not new to Australia.
Financial institutions have explored Sharia-compliant products for many years as Australia’s Muslim population and business community have grown.
The sector operates on principles intended to avoid traditional interest-based lending structures, instead using alternative arrangements designed to comply with Islamic law.
Supporters argue these products help ensure that Muslim Australians can participate fully in the financial system while remaining consistent with their religious beliefs.
They also point out that participation is voluntary.
No customer is required to use Islamic finance products if they prefer conventional banking services.
Critics, however, argue that the issue goes beyond customer choice.
Some believe financial institutions should avoid creating separate frameworks based on religion because doing so risks encouraging division rather than integration.
Those concerns are reflected in One Nation’s criticism.
The party has repeatedly campaigned on issues involving national cohesion and cultural integration, making the NAB controversy a natural extension of themes it has promoted for many years.
The timing is also politically significant.
One Nation is currently enjoying increased visibility through its fundraising campaigns, public meetings and growing presence in national political discussions.
Issues involving immigration, religion and multiculturalism have become central parts of the party’s messaging.
As a result, disputes such as this often attract substantial attention from supporters.
The debate has also highlighted the broader challenge facing major corporations operating in a multicultural society.
Businesses increasingly serve customers from a wide range of cultural and religious backgrounds.
That often creates pressure to offer products and services tailored to specific needs.
For some Australians, that flexibility is evidence of a responsive and inclusive economy.
For others, it raises concerns about whether different standards are being applied to different groups.
The disagreement is unlikely to be resolved anytime soon because it touches on deeper questions about identity, inclusion and the role of religion in public life.
Those issues have long been politically sensitive in Australia and continue to generate strong reactions across the political spectrum.
For One Nation, the NAB dispute provides another opportunity to reinforce its broader arguments about national culture and institutional change.
For NAB, it is likely to be viewed as part of the challenge of serving a diverse customer base while navigating increasingly polarised public debates.
Whether the controversy fades quickly or develops into a larger political issue remains to be seen.
What is already clear is that a banking product once known mainly within specialist finance circles has suddenly become part of a much larger national conversation.