Australia’s housing affordability crisis has taken another political turn after new figures revealed more than 51,000 non-citizens have accessed the federal government’s 5 per cent home deposit scheme.
The numbers have reignited a growing debate about who should benefit from taxpayer-backed housing assistance at a time when many Australians believe home ownership is becoming increasingly difficult to achieve.
For some, the figures demonstrate that Australia remains a country where people who build their lives here should have opportunities to purchase a home.
For others, the statistics raise uncomfortable questions about priorities as many Australian citizens continue to struggle with soaring property prices, elevated mortgage repayments and rising living costs.
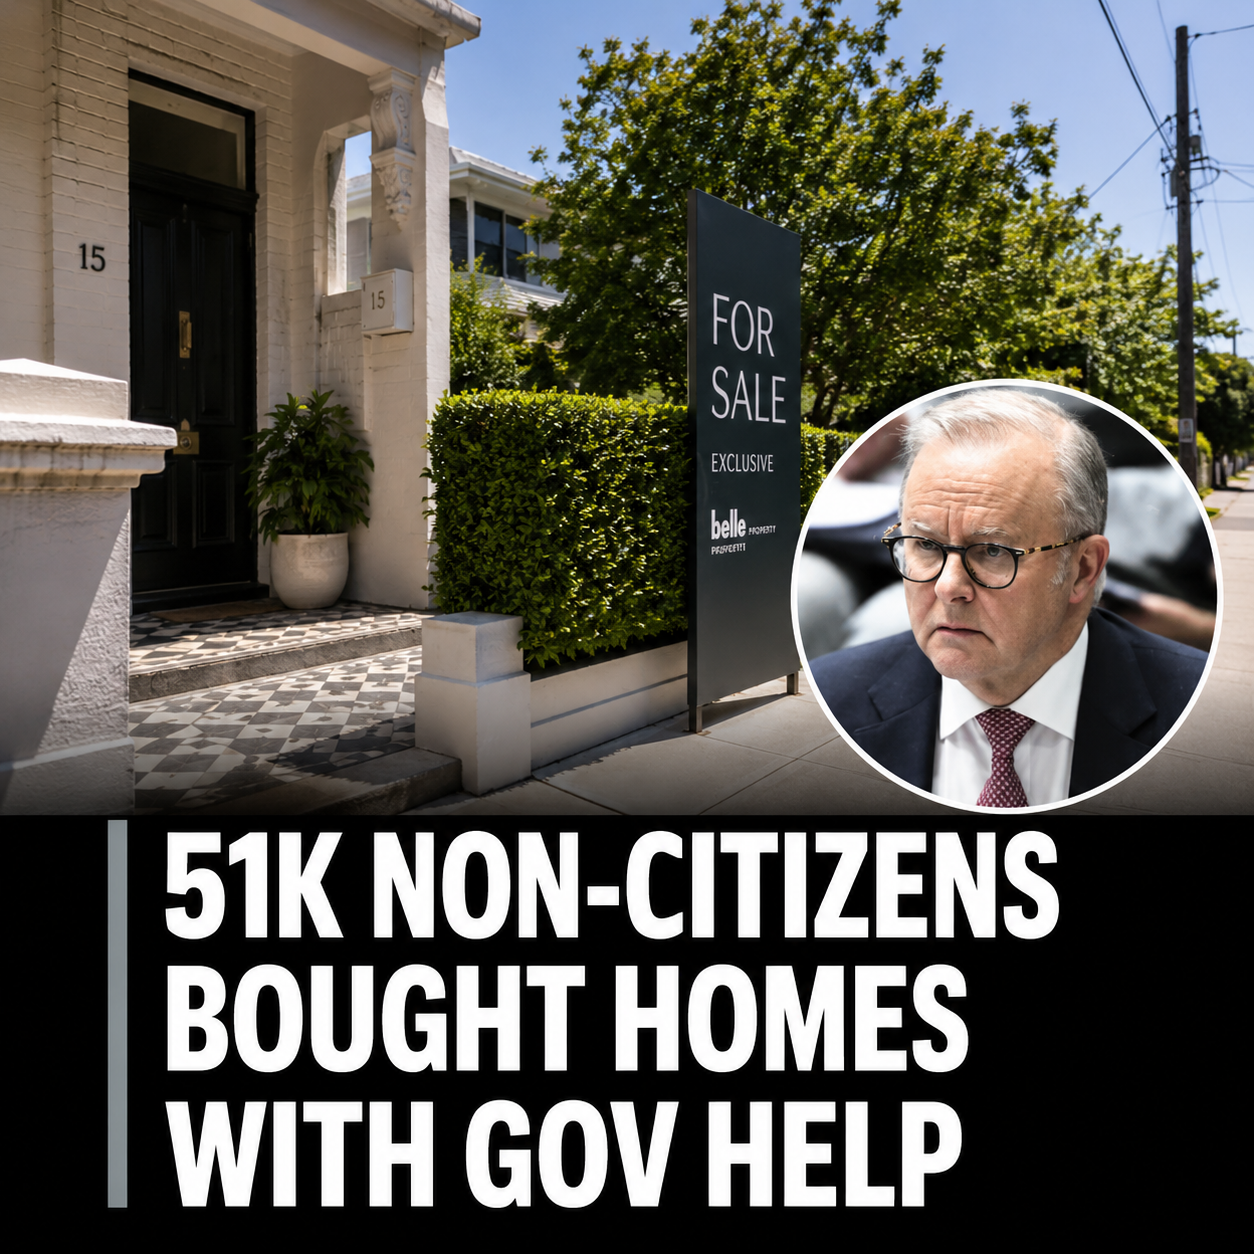
The scheme allows eligible first-home buyers to enter the property market with a deposit as low as 5 per cent, avoiding the need for lenders mortgage insurance through a government guarantee.
For many households, that support can make the difference between buying a home and remaining in the rental market for years longer.
Housing affordability has become one of the defining economic issues facing Australia.
Property values across many parts of the country have increased substantially over the past decade, while wages have often struggled to keep pace with the cost of entering the market.
As a result, saving a traditional 20 per cent deposit has become an increasingly difficult challenge for many young Australians.
Government-backed deposit schemes were originally promoted as a way of helping first-home buyers overcome that barrier.
However, the latest figures have shifted public attention toward who is accessing those benefits and whether the program is meeting community expectations.
The debate is occurring against a backdrop of broader concerns about housing supply.
Australia continues to experience strong population growth while many regions face persistent shortages of available homes.
Construction costs remain elevated, planning delays continue to affect development pipelines and rental vacancy rates remain tight in numerous locations.
These pressures have created an environment where competition for housing is intense regardless of whether someone is looking to buy or rent.
For first-home buyers, every policy connected to housing now attracts significant scrutiny.
Many young families feel they are competing in a market that has become increasingly difficult to navigate.
High prices, rising insurance costs, council rates, utility bills and mortgage repayments have combined to create financial pressure that extends well beyond the initial purchase of a property.
This is one reason housing policies have become such a politically sensitive issue.
They directly affect family budgets, long-term wealth creation and perceptions of economic fairness.
The latest revelations have also brought renewed attention to the government’s role as guarantor.
Under the scheme, the Commonwealth effectively helps eligible buyers enter the market by guaranteeing part of the loan.
If a borrower defaults under certain circumstances, taxpayers may ultimately bear some of the associated risk.
Supporters argue that default rates remain relatively low and that helping more people secure stable housing can deliver long-term social and economic benefits.
Critics counter that taxpayers should have confidence that public resources are being directed toward the groups the community expects to receive assistance.
That disagreement sits at the heart of the current political debate.
Questions about immigration and housing have increasingly become linked in public discussion.
Australia relies heavily on migration to support economic growth, workforce participation and population expansion.
Many industries depend on skilled migrants and temporary residents to fill labour shortages.
At the same time, rapid population growth can increase demand for housing, particularly in major cities where supply struggles to keep pace.
This has led some voters to ask whether governments should focus more heavily on increasing housing supply before expanding programs that support additional demand.
Others argue the real problem is not who accesses assistance but the chronic shortage of homes being built.
From that perspective, debates about eligibility risk distracting from the larger challenge facing policymakers.
Australia simply does not appear to be building enough housing to meet long-term demand.
Economists, industry groups and housing advocates have repeatedly pointed to supply constraints as a major contributor to affordability problems.
Without significant increases in construction activity, many experts believe pressure on prices and rents could continue regardless of changes to individual support programs.
The issue is particularly important for younger generations.
Many Australians in their twenties and thirties worry that home ownership is becoming increasingly unattainable compared with previous generations.
For them, housing is not merely an investment issue.
It is a question of financial security, family formation and future economic stability.
The political implications are significant.
Housing affordability consistently ranks among the most important issues raised by voters across the country.
As governments search for solutions, every policy decision is likely to face close examination from both supporters and critics.
The revelation that more than 51,000 non-citizens have accessed the deposit scheme is therefore likely to remain part of a broader conversation about housing, migration and public spending.
What happens next may depend less on the political argument itself and more on whether governments can deliver meaningful improvements in affordability.
If housing supply increases and price pressures ease, public concerns may soften.
If affordability continues to deteriorate, scrutiny of taxpayer-backed programs is likely to intensify.
For many Australians, the underlying question remains remarkably simple.
In a country facing one of its toughest housing challenges in decades, how should limited support be allocated and who should be first in line when government assistance is available?
That question is likely to remain at the centre of Australia’s housing debate for years to come.