A Sydney family’s dream of home ownership has become an unexpected lesson in how quickly property markets can change after the value of their newly purchased townhouse reportedly dropped by around $140,000 within hours of settlement.
The experience has attracted widespread attention as Australia’s housing market continues adjusting to changing economic conditions, shifting buyer confidence and major policy reforms announced in this year’s federal budget.
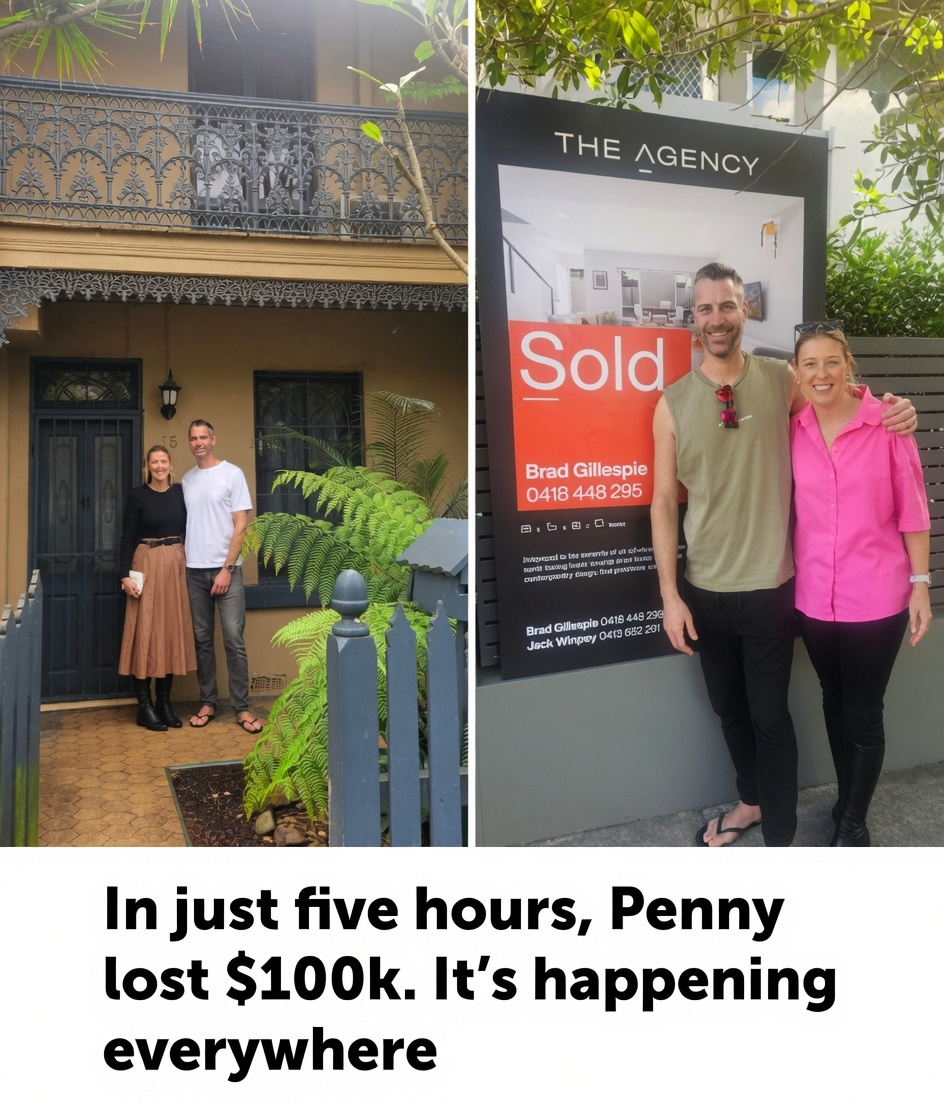
According to published reports, Penny and her husband purchased a three-bedroom townhouse in Sydney just five hours before the federal budget was handed down. Shortly afterwards, market sentiment changed dramatically as investors and buyers began assessing the likely impact of the government’s housing and taxation reforms, contributing to renewed weakness across Sydney’s residential property market.
While the family has no intention of immediately selling the property, updated market estimates indicate the home’s value has fallen by approximately $140,000 since the purchase. Their experience has become one of the most widely discussed examples of the risks involved when buying property during periods of rapid market change.
For many Australians, property has long been viewed as one of the country’s safest long-term investments. Decades of generally rising home values have created an expectation that purchasing sooner rather than later usually results in capital growth. However, market analysts note that no property market moves in only one direction, and periods of correction are a normal part of longer economic cycles.
Sydney, in particular, has experienced extraordinary price growth over the past two decades. Strong population growth, limited housing supply in many established suburbs, historically low interest rates during parts of the previous decade and sustained investor demand all contributed to significant increases in dwelling values.
Those conditions have changed considerably.
Higher borrowing costs, weaker affordability, slower buyer activity and uncertainty surrounding taxation settings have all reduced demand across several major Australian housing markets. Sydney and Melbourne have recorded some of the country’s largest price declines during recent months.
Property economists say housing markets are influenced by a combination of factors rather than a single event. Interest rates affect borrowing capacity, employment influences household confidence, population growth shapes housing demand, while government policy can alter the attractiveness of residential property as an investment.
Following this year’s federal budget, significant attention has focused on changes affecting property investors, particularly reforms involving taxation arrangements. Many analysts believe those changes have encouraged some investors to leave the market while prompting other buyers to delay purchasing until prices stabilise.
As demand softens, sellers often need to reduce asking prices to complete transactions, leading to broader declines in property values.
Several financial institutions and economists have since revised their forecasts for Australia’s housing market, with some predicting additional falls before prices eventually stabilise. Forecasts differ considerably, highlighting the uncertainty surrounding the market’s next phase.
For homeowners like Penny and her family, the immediate reduction in estimated value may be confronting emotionally, but financial advisers often point out that unrealised paper losses do not necessarily translate into actual financial losses unless a property is sold during the downturn.
Many Australians purchase homes intending to live in them for many years rather than trade them over short periods. Historically, residential property values have experienced multiple cycles of growth and decline, with long-term ownership generally reducing exposure to temporary market fluctuations.
Nevertheless, falling prices can create genuine financial challenges for some households.
Owners who purchased with relatively small deposits may find themselves with reduced equity if market values continue falling. In more severe situations, borrowers could owe more on their mortgage than the property’s market value, a situation commonly referred to as negative equity.
Negative equity does not automatically create financial hardship provided borrowers continue making repayments and do not need to sell. However, it can reduce financial flexibility by making refinancing more difficult or limiting options if circumstances change.
First-home buyers face a particularly complex environment.
Lower prices may eventually improve affordability for those yet to purchase. However, declining markets often create hesitation because prospective buyers worry that waiting could result in even lower prices in coming months.
This uncertainty can become self-reinforcing. As buyers delay purchasing, transaction volumes fall, creating additional downward pressure on prices.
Recent market data has reflected that pattern, with auction clearance rates weakening and fewer successful sales recorded across Sydney compared with previous years.
The broader Australian housing market remains highly diverse.
Conditions differ significantly between cities, regional centres and individual suburbs. Some locations continue recording relatively stable prices due to strong local demand or constrained housing supply, while others have experienced much sharper corrections.
Even within Sydney, price movements vary considerably depending on housing type, neighbourhood, affordability and buyer demographics. Premium suburbs may behave differently from middle-ring or outer suburban markets, while apartments, townhouses and detached houses can follow separate trends.
Experts frequently caution against assuming that national housing statistics accurately describe every local market.
Australia’s housing affordability challenges also extend beyond short-term price movements.
Many economists argue that high purchase prices accumulated over decades remain one of the country’s most significant economic and social issues. Although falling prices may improve affordability for future buyers, they also reduce household wealth for existing owners and may affect consumer spending if confidence weakens.
Governments therefore face the difficult task of balancing affordability for new buyers with financial stability for existing homeowners and the broader economy.
The federal government’s longer-term housing strategy also includes measures intended to increase housing supply through new construction over coming years. However, many analysts note that increasing supply takes time, meaning immediate market movements are still largely driven by interest rates, financing conditions and buyer confidence.
Australia’s property market has experienced numerous periods of correction over previous decades before eventually returning to growth. Past performance, however, does not guarantee future outcomes, and economists continue to debate how long the current downturn may last.
Some analysts believe prices could stabilise once buyers adjust to the new policy environment and interest rate expectations become clearer. Others argue additional declines remain possible if economic conditions weaken further or borrowing costs remain elevated for an extended period.
For households considering entering the market, financial advisers generally recommend focusing on long-term affordability rather than attempting to perfectly time market movements. Purchasing decisions typically depend on stable employment, manageable mortgage repayments, personal circumstances and the intention to hold the property over many years.
Penny’s experience illustrates how rapidly housing market conditions can shift. Purchasing a home only hours before a significant policy announcement placed her family on the wrong side of a sudden market adjustment, but it also highlights the reality that property investment, despite its reputation for long-term stability, is never entirely free from risk.
As Australia’s housing market continues adapting to new economic conditions, buyers, sellers, investors and policymakers alike will be closely watching whether the recent decline represents a temporary correction or the beginning of a more prolonged adjustment in residential property values.